Greenlight: For Families

Screenshots
Details
- Rating
- 10.87K reviews
- Version
- 8.6.0
- Developer
- Greenlight Financial Technology, Inc.
Analysis by Norviv
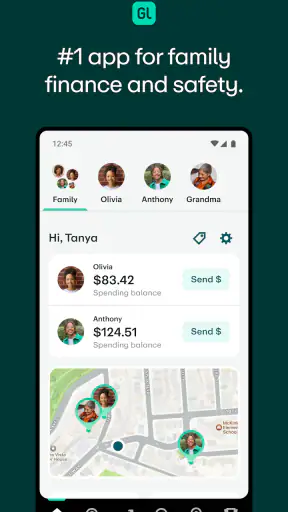
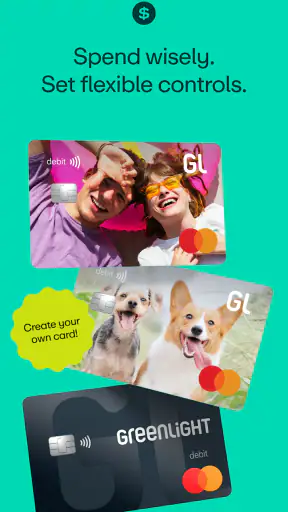
When I look at a money app for a family, I do not judge it only by whether a child can tap a card at a shop. I want to know whether the adults can stay involved without turning every small purchase into a conversation, and whether the young person gets a useful sense of independence instead of simply receiving another payment tool. That is the space Greenlight: For Families tries to occupy: a finance app built around a debit card for kids and teens, with parents managing the experience through the app.
I spent time considering it from the point of view of a household sharing responsibility for everyday spending. The appeal is easy to understand. A parent can remain part of the process, while a child or teenager gets a more concrete way to learn about spending than asking for cash each time. The important distinction is that this is not just a banking app aimed at adults with a smaller interface. Its value comes from the relationship between the parent’s management role and the young person’s spending role.
How Greenlight fits into a shared household
A realistic example is a teenager heading to school with money for lunch, a small after-school purchase, or an agreed activity. In a traditional arrangement, the parent might hand over cash, send money through an ordinary payment service, or use an adult account and hope the spending stays within the intended limit. Greenlight creates a more deliberate middle ground. The young person uses the debit card, while the parent keeps the family’s financial routine connected to the app.
That arrangement works best when everyone understands the boundaries before the card is used. The parent is not merely giving a replacement for cash; the adult is choosing to stay involved in how money is provided and monitored. The child or teen, meanwhile, needs to see the card as a responsibility rather than an unlimited source of funds. In my view, that shared understanding matters more than the card itself.
The app is free to download, and its content rating is Everyone, which makes the product easy to consider for a broad household audience. Still, “suitable for everyone” should not be confused with “equally useful for everyone.” A younger child may need much more explanation and supervision than an older teenager. The interface can support a family conversation, but it cannot replace one.
Greenlight comes from Greenlight Financial Technology, Inc., and it has been available since December 23, 2016. That history helps explain why the product is recognizable in the family finance space, but I would not choose it simply because it has been around for a while. I would choose it when the household actually wants a parent-managed spending arrangement rather than a conventional adult banking account.
What the parent-managed model changes
The strongest idea here is the separation of roles. The adult remains responsible for the overall setup, while the child or teen gets a practical way to use money. That can make ordinary moments more educational. Instead of saying “you spent too much,” a parent can discuss the spending pattern that the app makes visible and connect it to the next decision.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
This also gives families a shared reference point. If one parent usually handles money and another parent occasionally gives cash, the app can help keep the arrangement less dependent on memory. That does not automatically solve coordination problems, but it gives the household a defined place to check before sending money or approving a plan.
There is a trade-off. A parent who wants complete separation from a child’s everyday spending may find this model too involved. Likewise, a teenager who is ready for the independence of an ordinary personal account may see parental management as restrictive. I would not present that friction as a flaw in every household; it is a question of timing and expectations.
Setting boundaries before the first purchase
The most useful setup work happens before the card becomes part of a daily routine. I would sit down with the child and decide what the money is for, which purchases need a conversation, and how the family will handle mistakes. The app can be the place where the parent manages the arrangement, but the household still needs its own rules in plain language.
For example, imagine a parent adding money for school lunches while the teenager also wants to buy a snack after practice. The key question is not just whether the purchase is technically possible. It is whether the teenager understands which part of the available balance is intended for lunch and which part is flexible. Without that distinction, a card can make money feel less limited than it really is.
I also recommend agreeing on what happens when the balance is low. Will the child wait until the next planned addition, ask before receiving more, or use another method for an essential expense? This is one of the less obvious benefits of a managed card: it gives the family a chance to define a repeatable process instead of negotiating from scratch at the checkout.
The best boundary is one that the child can explain back without opening the app. If the rule only exists in a parent’s head, the technology is doing too much of the parenting. Greenlight is more useful when the app reinforces a household agreement rather than silently becoming the agreement.
Account boundaries and shared devices
Families should also think about who is using which device and account. A shared tablet or family phone can be convenient, but finance information deserves deliberate handling. I would avoid treating a shared device as if every family member has the same role. The parent should manage the adult side, while the child should only use the part of the experience intended for their participation.
This is especially important in households with several children. Each child may have a different level of maturity, a different spending purpose, and a different conversation with the parent. The app should not become an excuse to compare siblings constantly. A better approach is to use each child’s activity as a starting point for an individual discussion about choices and responsibility.
Before relying on the app during a trip or a busy school day, I would make sure everyone knows how the household will communicate if something goes wrong. That could mean a lost card, an unexpected purchase, or simply a child who is unsure whether a planned expense is acceptable. The app helps coordinate money, but a backup communication plan prevents a small problem from becoming an emergency.
Why the setup can feel more demanding than cash
Cash is simple in one sense: hand it over, and the child knows exactly what is available. A managed debit card introduces more structure, which means more decisions at the beginning. Parents need to be comfortable taking an active role, and children need to understand that the card does not remove limits.
That initial effort is worthwhile for families that want a repeatable system, but it may feel unnecessary for occasional pocket money. If a child only needs a small amount for a rare outing, ordinary cash may be faster and less complicated. Greenlight makes more sense when spending happens regularly enough for the family to benefit from an organized routine.
Coordinating money between parents and children
In my experience, the coordination side is where this type of app earns its place. The card is visible to the child, while the management relationship stays with the parent. That creates an opportunity to make money discussions more specific. Instead of arguing about whether a teenager is “careful,” the family can talk about a particular choice, a recurring need, or a planned expense.
For households with two adults, consistency matters. If one parent treats the card as a tightly controlled allowance and the other treats it as an open-ended backup, the child receives mixed signals. I would agree on a simple shared approach: what the card is mainly used for, how new money is handled, and when the adults review the arrangement together.
This does not mean every parent needs to inspect every purchase immediately. Constant checking can make the experience feel like surveillance, especially for an older teen. A calmer routine may be better: review spending at an agreed time, ask about anything unclear, and focus on patterns rather than reacting dramatically to every small transaction.
That balance is one of the app’s most important practical challenges. The parent-managed model is valuable because it keeps adults involved, but too much involvement can undermine the independence the product is supposed to teach. I would gradually shift the conversation from permission to planning as the child demonstrates better judgment.
Using the app as a teaching tool
A useful workflow is to connect spending to a short weekly check-in. The parent and child can look at what the money was intended to cover, what actually happened, and whether the next amount should be planned differently. This is more constructive than using the app only when something goes wrong.
For a younger child, the conversation might focus on distinguishing a need from an impulse. For a teenager, it can move toward planning for a larger purchase, keeping money available for transport, or recognizing how several small purchases affect the remaining balance. The app provides the setting for those conversations, but the parent’s questions determine whether the experience feels educational or punitive.
Another practical tip is to avoid topping up money simply because the balance has reached zero. If the household always restores the balance immediately, the child may learn that limits are temporary obstacles. A planned schedule, with exceptions for genuine needs, gives the card a clearer meaning and makes the available money easier to understand.
Greenlight is also a better fit for families that want one shared routine than for adults who prefer each parent to manage money separately with no coordination. The more people involved, the more important it becomes to decide who communicates changes to the child. Otherwise, the app may show one financial plan while the family is following another verbally.
Age, trust, and growing independence
The age rating makes the app broadly approachable, but the right level of freedom depends on the child, not just the number of birthdays. A responsible younger user may handle a defined spending purpose well, while an older teenager may still need clear limits around discretionary money. I would begin with a narrow, understandable use case and expand responsibility only when the child can manage it consistently.
Trust should grow in stages. Giving a child a card does not prove that the child is ready for unrestricted spending, just as managing the card does not prove that a parent needs to approve every decision. The healthiest arrangement is one where both sides know what is being trusted: perhaps the child is trusted to manage lunch money, but not every household expense; perhaps the parent is trusted to provide funds on schedule, but not to criticize every small choice.
This is where Greenlight differs from a standard payment app used between adults. An ordinary peer-to-peer service may be excellent for reimbursing a friend or sending money quickly, but it usually does not create the same parent-child learning structure. On the other hand, a traditional bank account may be preferable for an older teen who needs a broader adult-style banking relationship and is ready for less direct supervision.
The app is not the right choice for a family that wants to hide financial decisions from children completely. It is also not ideal if the child is expected to manage money independently but the parent is unwilling to establish consistent rules. The product’s central strength—parental involvement—is also the reason some households will outgrow it or reject it.
Handling mistakes without turning them into punishment
Everyday spending mistakes are inevitable. A child may misunderstand a rule, forget the purpose of a balance, or make a purchase that seemed reasonable in the moment. I would use those incidents to refine the family’s system. Was the rule unclear? Was the amount too difficult to track? Did the child need a reminder before a particular type of outing?
A managed card can make these moments easier to discuss because the family has a concrete event to examine. But the parent should resist using the app as a scoreboard of failures. If every error leads to a sudden restriction, the child may focus on avoiding detection rather than learning to make better choices.
Privacy and dignity matter too. In a multi-child household, financial conversations should not become public comparisons. Each child needs an age-appropriate explanation of their own responsibilities. That approach keeps the app focused on learning and reduces the chance that shared-device use turns into unnecessary family tension.
How it compares with familiar alternatives
Compared with cash, Greenlight offers a more organized way to connect a child’s spending with parental management. Cash remains attractive for simplicity, privacy from devices, and one-off situations. I would choose cash for a short outing where the amount is clear and no ongoing record is needed. I would choose Greenlight when the family wants a continuing routine and a card-based experience.
Compared with an ordinary adult debit account, the family-focused model is more suitable when the child still needs guidance. The adult account may offer greater independence, but that can be a disadvantage if the purpose is to teach spending gradually. For an older teenager preparing to handle money without close oversight, the ordinary account may eventually be the better next step.
Compared with person-to-person payment apps, Greenlight is more intentional about the parent-child relationship. A quick transfer app can solve a single request, such as sending money for a meal, but repeated transfers can become messy and reactive. Greenlight is better suited to a household that wants the card and the app to form part of a planned system rather than a series of emergency payments.
There is no universal winner. The right alternative depends on whether the family values simplicity, independence, or guided learning most. My judgment is that Greenlight occupies the guided-learning middle: more structured than cash, more family-oriented than an adult account, and more deliberate than sending money whenever a child asks.
What the public response suggests
The app has an average rating of 4.7 from around 85 thousand ratings, with over a million installs. Those figures show that the concept has reached a substantial audience and that many users find the basic arrangement useful. They should not be treated as a guarantee that every family will enjoy the same experience. Finance apps are especially sensitive to household expectations, account roles, and how carefully the initial setup is handled.
The current version is 8.6.0, and it requires iOS or Android version 10 or later. That makes device compatibility worth checking before a parent plans to move the whole household onto the app. A family using older phones may face a practical barrier even if the service itself sounds suitable.
I would also remember that a free download does not mean the experience is identical to every other free finance app. The important question is whether the family wants this particular managed-card model and is willing to build routines around it. Downloading it casually without agreeing on responsibilities may lead to disappointment, while a prepared household is more likely to understand what the app is meant to do.
My household verdict
I recommend Greenlight to parents who want to give a child or teen practical access to spending while staying involved in the process. It is especially compelling for regular school, activity, or allowance routines where cash feels inconvenient and an adult account feels too independent. The app’s real value is not simply that it puts a card in a young person’s hand; it gives the household a framework for discussing money as it is used.
I would skip it if the family wants a completely hands-off experience, if the child only needs occasional pocket money, or if the teenager is already ready for a more independent banking arrangement. I would also hesitate when parents disagree about the rules, because no app can compensate for inconsistent decisions between adults.
For the best results, I would start with one clear spending purpose, explain the boundary before the first purchase, establish how the family handles low balances and mistakes, and review the routine periodically rather than reacting to every transaction. That approach keeps the card useful without making the child feel constantly watched.
Overall, Greenlight is a thoughtful finance app for families that want to turn everyday spending into a gradual lesson in responsibility. It works best when parents treat management as guidance, children understand what they are responsible for, and everyone agrees on the limits. If your household wants a shared money routine rather than just another way to send funds, this is one of the more focused options to consider.
Frequently Asked Questions
01What is Greenlight: For Families, and who is it designed for?
Greenlight: For Families is a family-focused financial app designed to help parents teach children and teenagers how to manage money. It typically combines a parent-controlled account, a spending card for the child, allowance and chore tools, savings features, and activity monitoring. The exact features available can depend on the selected plan, the child’s age, and the family’s location.
02Do parents remain in control of their child’s spending?
Yes, parental control is one of the app’s main features. Parents can generally add money, review transactions, receive spending notifications, set spending limits, and manage where the connected card can be used. Before downloading, families should still review the current controls and merchant restrictions, because some options may vary by subscription level, card type, or updates to Greenlight’s policies.
03Does Greenlight: For Families help children learn about saving and budgeting?
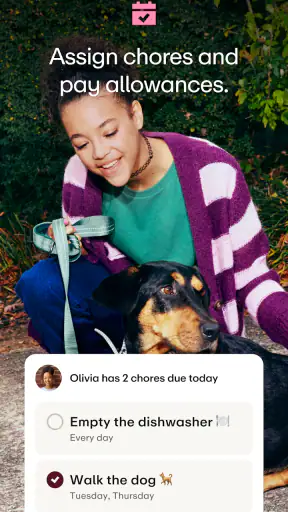
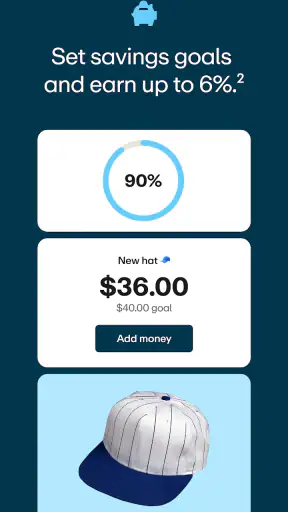
The app is designed to make money lessons practical rather than purely theoretical. Parents can usually assign allowances, connect payments to chores, create savings goals, and discuss spending activity with their children. These tools can encourage better habits, but the app does not replace parental guidance. Children still need regular conversations about needs, wants, budgeting, privacy, and responsible card use.
04Are there fees or subscription costs associated with Greenlight?
Greenlight generally operates through a paid subscription model, and the price may depend on the plan selected by the family. Some plans can include additional benefits or optional features, while card delivery, replacement, or other services may have separate terms. Check the current pricing page in your country before signing up, and confirm renewal conditions so there are no unexpected recurring charges.
05Is Greenlight: For Families safe for children to use?
The service is built around parental supervision, account controls, transaction visibility, and a card intended for supervised family spending. However, no financial app is completely risk-free. Parents should use strong passwords, enable available security features, discuss scams and card safety with their children, and monitor account activity. It is also important to read the privacy policy and understand how personal and financial data are handled.


